Market overview and structural scope of the Mineral-Fortified-Beverages Market
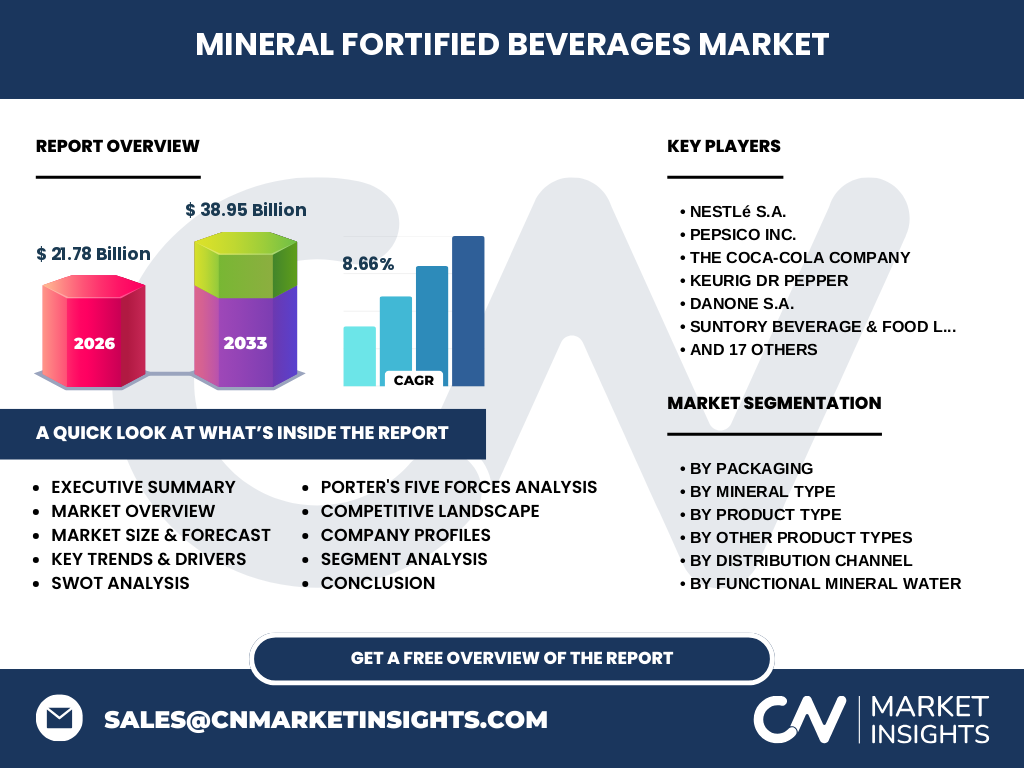
The Mineral-Fortified-Beverages Market represents a critical functional beverage sector, valued at $21.78 Billion in 2026. Our analysis indicates that consumer demand for preventative healthcare drives this industry, integrating essential micronutrients like calcium and magnesium into everyday liquid refreshment to combat nutritional gaps.
Key market drivers, restraints, challenges, and opportunities shaping the Mineral-Fortified-Beverages Market
Growth is propelled by rising chronic lifestyle diseases and wellness adoption, though high cold-chain logistics costs act as a restraint. Regulatory hurdles from agencies like the FDA complicate labeling claims, creating prime opportunities for brands utilizing bioavailable mineral compounds.
The Shift Toward Functional Hydration and Emerging Industry Trends
Consumer preference is shifting away from sugary sodas toward functional mineral water and electrolyte-enhanced formulations. Based on our research, clean-label sourcing and alkaline variants dominate new product pipelines among agile market innovators.
COVID-19 Impact Analysis and Post-Pandemic Recovery Trajectory
The pandemic dramatically accelerated health consciousness, causing an unprecedented surge in demand for immunity-boosting fortified beverages. Supply chain disruptions temporarily choked raw material procurement, but post-pandemic recovery has proven robust with accelerated retail channel shifts.
Competitive benchmarking and strategic dynamics within the global landscape
Market concentration is moderately high, dominated by multinationals like The Coca-Cola Company, PepsiCo Inc., and Nestlé S.A. Strategic M&A activity targets emerging functional beverage upstarts to capture high-margin lifestyle consumer segments rapidly.
Executive summary of key findings for the Mineral-Fortified-Beverages Market industry trends
Our comprehensive findings show the Mineral-Fortified-Beverages Market expanding at a stellar CAGR of 8.66%. Strategic investments in sustainable packaging and proprietary mineral bioavailability technologies will separate market leaders from legacy laggards over the next decade.
Market forecast trajectory from 2027 to 2033
The data projects stellar expansion, scaling the market from its baseline to reach $38.95 Billion by 2033. This sustained trajectory highlights a compound annual growth rate that outperforms traditional non-alcoholic beverage categories significantly.
Comprehensive segmentation analysis across product, mineral, and packaging categories
Segmentation spans multiple vectors including mineral types like Calcium, Magnesium, and Zinc, alongside product variations from functional waters to sports drinks. Packaging categories heavily favor sustainable bottles and eco-friendly cartons to meet stringent environmental mandates.
Geographic distribution and macroeconomic regional performance
Regional performance varies widely, with North America leading consumption due to established wellness infrastructure. Meanwhile, Asia-Pacific exhibits the fastest adoption rates, driven by urban middle-class expansion and rising disposable incomes across key metropolitan hubs.
In-depth regional review of high-growth territories
North America remains the revenue epicenter, whereas Europe enforces rigorous EFSA health claim standards that shape clean-label formulations. Emerging Asian markets focus heavily on affordable, ready-to-mix mineral sachets tailored to local retail ecosystems.
Company profiles and strategic positioning of leading industry participants
Industry giants such as Danone S.A. and Suntory Beverage & Food Limited leverage extensive distribution networks to dominate retail shelves. Meanwhile, specialized challengers like Celsius Holdings and Evocus H2O Pvt. Ltd. carve out high-growth niches via targeted marketing.
Porter's Five Forces analysis of competitive pressures
Bargaining power of suppliers remains moderate due to specialized mineral sourcing requirements. Competitive rivalry is fierce, driven by continuous functional innovation and aggressive marketing campaigns from both beverage conglomerates and agile direct-to-consumer startups.
SWOT analysis highlighting internal capabilities and external market forces
Key strengths lie in robust distribution networks and proven formulation science. Weaknesses include high R&D expenditure for taste-masking minerals, while emerging direct-to-consumer channels offer lucrative expansion opportunities against strict regulatory threats.
Value chain analysis from raw mineral extraction to end-user consumption
The value chain begins with high-purity mineral compound sourcing, passing through advanced liquid blending facilities, and concluding via hypermarket and online retail channels. Optimizing cold-chain logistics remains vital for maintaining product integrity and shelf life.
Investment insights and high-potential areas for capital deployment
High-potential areas include plant-based mineral-fortified beverages and specialized electrolyte sports drinks. Investors should prioritize brands possessing proprietary taste-masking technology, as unpalatable mineral profiles remain a primary consumer adoption barrier.
Conclusion and strategic takeaways for industry stakeholders
The Mineral-Fortified-Beverages Market offers extraordinary potential for forward-thinking beverage manufacturers. Success hinges on balancing clinical efficacy claims with compelling sensory appeal, backed by agile supply chain execution across diverse global retail channels.
Research methodology utilized for baseline estimates and validation
Our methodology triangulates trade registry data, primary executive interviews with industry formulators, and secondary macroeconomic indicators. This rigorous triangulation ensures highly reliable market sizing and growth projections across all analyzed segments.
Scope of the report, coverage parameters, and analytical limitations
This report covers global consumption trends, regional regulatory frameworks, and comprehensive segment forecasts from 2027 to 2033. Limitations include unforeseen geopolitical trade shifts and rapid fluctuations in raw mineral commodity pricing.
Recent developments, corporate announcements, and strategic partnerships
Recent market activity features strategic acquisitions of functional water brands by multinational conglomerates to capture wellness demographics. Furthermore, major product launches focus on sustainable aluminum can packaging and clean-label mineral sachets.